Most businesses assume their general liability insurance covers pollution incidents. It doesn’t. A single spill, leak, or emission violation can trigger six-figure fines—and your standard policy won’t lift a finger. Here’s the fix: integrate Pollution Control Technologies into your risk strategy before regulators come knocking.
Why Traditional Insurance Fails on Pollution Risks
Standard commercial policies contain an absolute pollution exclusion clause. Read it. Buried in fine print: “any discharge, dispersal, seepage… of pollutants” is excluded unless you’ve bought specific coverage. And even then—most insurers demand proof you’re actively mitigating risk.
They don’t just want you to pay premiums. They want evidence you’re deploying real environmental risk management systems. Without them? Denial letters pile up faster than EPA citations.
How to Align Pollution Control Technologies With Your Insurance Strategy
Insurers reward proactive behavior. The right tech isn’t just about compliance—it’s leverage for lower deductibles, broader coverage terms, and faster claims processing. Start here:
Select Technologies That Match Your Operational Footprint
A dry cleaner needs vapor recovery—not wastewater bioreactors. A warehouse storing chemicals requires secondary containment sensors, not air scrubbers. Misalignment wastes capital and confuses underwriters.
Document Everything for Underwriting Submissions
Keep logs of system installations, maintenance records, and performance metrics. When you apply for pollution legal liability insurance, this data becomes your credibility currency.
| Technology Type | Typical Cost Range | Insurance Impact | Best For |
|---|---|---|---|
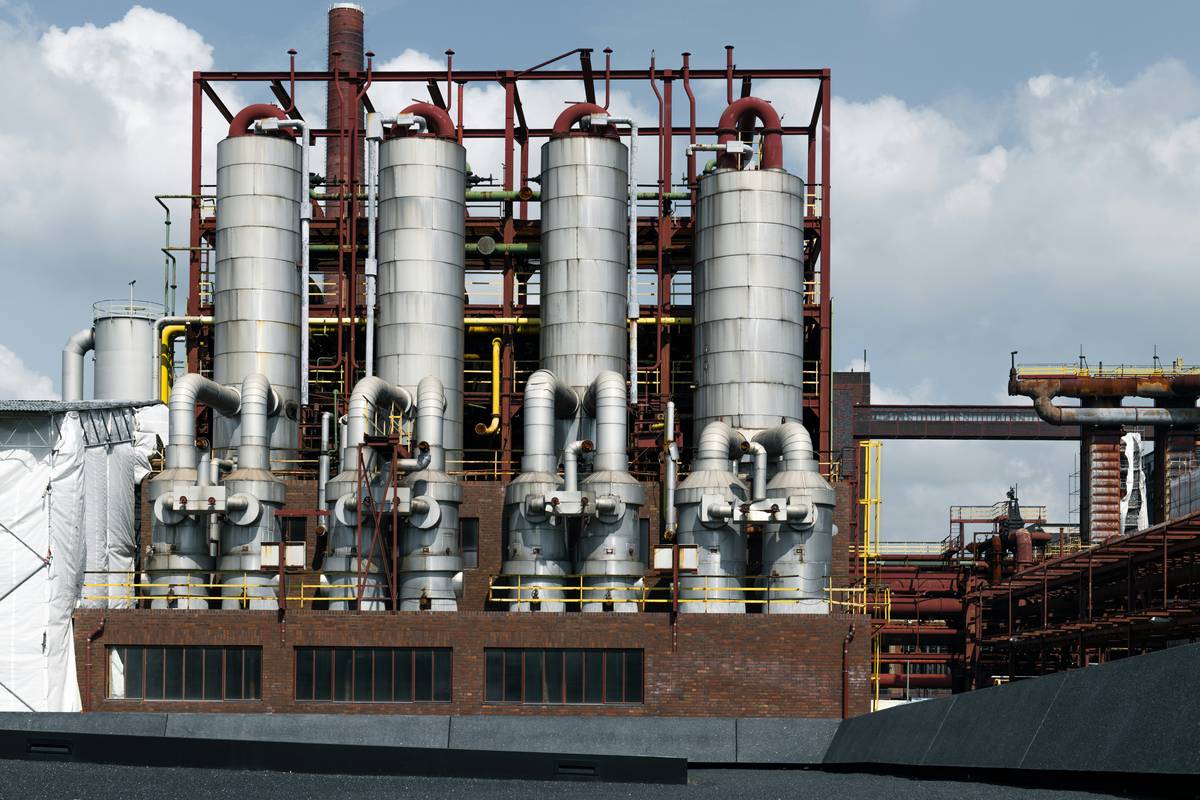
| Air Scrubbers (Wet/Dry) | $25,000 – $200,000 | Reduces air emission liability; often required for coverage | Manufacturing, chemical processing |
| Secondary Containment Systems | $10,000 – $150,000 | Lowers spill-related claim risk; may qualify for premium credits | Fuel depots, labs, storage facilities |
| Real-Time Leak Detection Sensors | $5,000 – $50,000 | Demonstrates active monitoring—key for cyber-environmental policies | Pipelines, underground tanks |
| Bioremediation Units | $15,000 – $80,000 | Shows remediation capability; supports post-incident coverage claims | Soil/water cleanup sites |
The Industry Secret: Insurers Quietly Prefer Retrofit Over Replacement
Here’s what brokers won’t tell you: carriers care less about cutting-edge gear and more about consistent, documented risk reduction. One midwestern distributor avoided a $300K coverage denial simply by adding IoT-enabled sump monitors to legacy tanks—no full system overhaul.
Why? Because underwriters know startups can’t afford $500K abatement systems. But they can afford incremental upgrades that prove operational diligence. That’s the real threshold—not technological perfection.
Frequently Asked Questions
Does environmental insurance cover pre-existing contamination?
No. Most policies exclude known or historical pollution. Full site assessments are required before binding coverage.
Are Pollution Control Technologies tax-deductible?
Often, yes—under Section 179 or as operational expenses. Consult a CPA, but expect write-offs for systems tied to regulatory compliance.
Can I get coverage without installing any technology?
Technically yes—but premiums skyrocket, deductibles balloon, and exclusions multiply. You’ll pay more to get less protection.